State of Rental Housing 2026: Performance, People & Technology
Explore the latest NAA and AppFolio findings on AI, workload, scale, and the gap between today’s results and tomorrow's potential.
Table of Contents
Executive Summary
The rental housing industry is operating from a position of relative stability but actively seeking ways to improve performance. Most respondents report positive company performance, yet many believe their organizations are operating below full potential. Across financial performance, workforce management and technology utilization, respondents consistently identify opportunities to unlock additional value through stronger execution, workforce development and operational efficiency.
Survey respondents continue to identify operational efficiency as the industry's most pressing challenge. Manual processes, staffing constraints, inconsistent execution and external market conditions continue to limit performance, while staff training, standardized operating procedures, artificial intelligence (AI), automation and technology modernization emerge as the most frequently identified paths to improvement. Together, these findings suggest that operators increasingly view performance as a function of how effectively people, processes and technology work together. That framing reflects a broader shift underway across the industry: away from measuring success purely by task efficiency and toward managing for outcomes and value creation across the whole operation.
Technology continues to move from a support function to a strategic driver of operational performance. Organizations report growing value from AI, automation, resident self-service tools, analytics and standardized workflows. However, challenges related to adoption, integration, training and organizational readiness remain significant barriers to realizing their full benefits. Respondents reporting the greatest AI impact are also more likely to report stronger Net Operating Income (NOI) growth, highlighting the importance of successful implementation.
While workforce engagement remains strong, employees continue to spend much of their time on routine and reactive activities. Role-level analysis shows that ideal work allocation varies by function, with leadership roles favoring strategic work and operational roles maintaining a greater emphasis on routine responsibilities.
Introduction
The 2026 rental housing landscape is being shaped by a broader economy that remains resilient but increasingly uneven. The U.S. economy continues to expand at a moderate pace, supported by steady employment, consumer spending and business investment, especially in technology and AI. Yet that resilience continues to be tested by persistent inflation, elevated interest rates, geopolitical volatility and mounting household financial pressures. For consumers, the stubborn inflation of the past five and a half years translates into prices that are substantially higher than households experienced before the pandemic, while wage gains struggle to keep pace. At the same time, higher mortgage rates, coupled with high home prices continue to limit homeownership, reinforcing rental housing as a critical part of the nation’s housing infrastructure.
Apartment market fundamentals reflect these economic conditions, as the sector transitions from the peak of a multi-year construction boom — one of the largest waves of new apartment supply in recent history — toward gradual stabilization. New deliveries remain elevated in many markets, especially across parts of the Sun Belt, but construction activity is slowing and the development pipeline is beginning to normalize. In tandem with new supply, demand continues to drive absorption, placing a floor under rent growth. Notably, however, market performance has been diverging across geographies and fundamentals are highly localized, a departure from the trends of prior years. Coastal and lower-supply markets, particularly in the Midwest and Northeast, are showing stronger rent growth, while metros that experienced the largest construction wave continue to face heavier competition, concessions and pressure on pricing power.
To evaluate industry performance against this backdrop, the National Apartment Association (NAA) partnered with AppFolio to conduct a nationwide survey of rental housing professionals. Conducted near the midpoint of 2026, the study captured comprehensive data on key performance drivers, operational challenges, workforce dynamics and technology adoption.
The survey findings highlight an industry that is generally stable, but not complacent. Most respondents report positive company performance and NOI growth, yet they also see meaningful untapped potential. Their leading challenges—operational efficiency, maximizing revenue, resident experience, along with staffing and technology implementation—reflect the realities of operating in a market where external conditions are no longer delivering broad-based tailwinds. Instead, performance gains increasingly depend on execution.
The research also underscores that technology and workforce strategy are becoming central to rental housing performance. Whether it is AI, automation, resident self-service tools or centralization, companies are increasingly relying on a multilayered approach to improve NOI and enable staff for more strategic work.
Rental Housing Operations: Performance
In 2026, we asked rental housing operators to characterize their company's overall performance, and most described it as "solid but inconsistent" rather than either "struggling" or "excelling across the board." A strong majority, 71%, said their company is "in the ballpark," with some wins alongside hits and misses. Only 20% described their company as being at the top of its game and consistently winning. By contrast, only a small minority rated their company's performance poorly, with 9% saying that their company is struggling, and 1% indicating that it is not even in the ballpark. Overall, the results suggest broad confidence in company performance, though most respondents see room for improvement rather than sustained top-tier execution.
Although 91% of respondents reported positive performance overall, perceptions strengthen notably as portfolio size increases. The performance trajectory data suggests that scale remains a meaningful competitive advantage. While approximately seven in 10 operators managing fewer than 10,000 units described their organizations as "in the ballpark," the experience of larger operators is notably different. More than half (55%) of respondents managing 10,000 or more units reported being "at the top of their game" and winning consistently, nearly three times the share reported among operators managing fewer than 1,000 units (19%). Simultaneously, large operators are significantly less likely to report struggling to achieve desired outcomes. While organizations of all sizes continue to navigate a challenging operating environment, the findings suggest that larger operators may be benefiting from greater operational efficiencies, more streamlined processes and broader organizational resources that support stronger performance outcomes.
Operators Continue to Identify Operational Efficiency as the Top Challenge
Amid an economy expanding at a moderating pace, along with rebalancing market fundamentals, respondents pointed out that companies' most important challenges are concentrated around core business performance and execution. Operational efficiencies ranked as the top concern by a wide margin, selected by 70% of respondents, followed by the 59% who expressed revenue concerns. This suggests that cost control, process improvement, occupancy, return on investment (ROI) and financial performance are the dominant priorities for companies today.
A second tier of challenges centers on customer value and systems evolution. Resident experience was selected by 43% of respondents, while implementing new technology and innovation was selected by 38%, indicating that companies are focused not only on internal performance but also on improving service quality and adopting new tools, including AI and system integrations. People-related issues remain important, with 31% identifying HR, staffing and recruitment as a top challenge.
The overall results suggest that companies are primarily focused on improving operational performance and profitability, while also balancing resident expectations, technology adoption and workforce needs.
A Majority Report Steady NOI Growth
With cashflow being a critical focus for all operators, industry professionals were asked to share how their portfolios' NOI changed during the past year. The findings indicate that even within the broader context of moderation in certain markets, NOI performance has generally improved over the past 12 months, though there was some uncertainty among respondents. Among those reporting a change, the largest share said NOI increased slightly, with 41% reporting growth of 1% to 4%. Another 25% said NOI increased significantly by 5% or more, meaning about two-thirds of respondents who provided a directional answer reported NOI growth.
At the same time, a smaller but notable share reported declines: 13% said NOI decreased slightly, while 6% reported a significant decrease. Another 15% reported no significant change. In aggregate, the figures point to broadly positive NOI momentum, but with mixed outcomes and a meaningful degree of uncertainty.
Market Conditions Remain the Primary Driver of NOI Performance
When asked what factors contributed the most to the company's NOI performance during the past 12 months, industry professionals indicated that market conditions were the leading driver of NOI performance, accounting for 54% of respondents. This suggests that factors such as rent growth, occupancy and interest rates have had the greatest perceived influence on financial outcomes. Market tailwinds seen during the pandemic, which lifted performance broadly in past cycles, are no longer a given. As those levers become less reliable, the operators best positioned to grow NOI will increasingly be the ones who can drive performance through execution, not just ride the market they happen to operate in.
Beyond the broader market environment, respondents also pointed to company-specific changes as important contributors. Portfolio changes were cited by 31%, while operating expenses and workforce changes were each cited by 27%, indicating that the levers most within an operator's control—acquisitions, dispositions, cost management, staffing, training and restructuring—matter just as much as the market conditions they can't control.
Operational changes unrelated to technology and the adoption of new technologies were each selected by 16% of respondents, suggesting these factors are viewed as secondary contributors to NOI performance. The results indicate that NOI outcomes are being shaped most strongly by external market forces, but internal portfolio, expense and workforce decisions also remain important drivers.
Notably, while market conditions were the leading factor associated with both NOI gains and declines, respondents reporting NOI increases were more likely to cite portfolio changes as a key contributor (42%), whereas those reporting NOI declines most frequently pointed to operating expenses (45%), highlighting the role of asset optimization and cost management in shaping financial performance. The dual appearance of market conditions as both a positive and negative driver reflects the reality that external factors such as rent growth, occupancy levels, supply pipelines, economic conditions and interest rates can influence performance in different ways across markets. These conditions create opportunities for growth in some areas while presenting challenges in other areas.
AI Impact Value and NOI Performance Move Together
The relationship between AI impact and NOI growth stands out. As perceptions of AI's value increase, so does the likelihood of reporting higher NOI growth. Respondents who reported that AI is revolutionizing performance were the most likely to report NOI growth, with 80% experiencing year-over-year NOI increases and only 11% reporting NOI declines. In contrast, among respondents who said AI has limited or no impact, just 56% reported NOI growth while 27% reported NOI declines. Respondents at the two ends of AI's perceived impact showed a clear NOI split: Those reporting revolutionizing impact were far more likely to report NOI growth than those reporting limited or no impact.
This suggests that organizations deriving measurable value from AI are also more likely to achieve stronger business outcomes. The results further indicate that the competitive advantage may not come from simply layering AI on top of existing workflows but from successfully implementing and integrating AI into day-to-day operations.
Gap Between Current and Full-Potential Business Performance
Although respondents generally reported stable performance, they also pointed to substantial opportunities for improvement. Across every business function evaluated, organizations reported a meaningful gap between their current performance and what they believe could be achieved if existing barriers were removed.
The largest gaps were concentrated in growth-oriented outcomes. NOI growth posted the largest gap, with only 34% of respondents rating current performance as strong or leading compared with 63% who believe they could achieve that level of performance under optimal conditions. Similarly, positive ratings for revenue growth increased from 36% to 64%, reflecting a widespread belief that operational constraints are limiting financial outcomes.
Largest Performance Gains Expected From Removing Operational Barriers
Technology management also stands out as a major area of unrealized potential. Thirty-eight percent of respondents rated current technology performance as strong or industry-leading, compared with 64% who believe their organizations could achieve those levels within the next 12 months if barriers were removed. This suggests that challenges related to system integration, workflow automation, AI adoption and technology consolidation remain significant impediments to business performance. This gap between current and achievable performance, most pronounced in technology and growth outcomes, points to a broader industry conversation about whether operators have the tools to move from reactive task management to proactive, outcome-driven operations.
By contrast, the smallest gaps were found in regulatory compliance and risk management, staff engagement and retention, and owner/investor satisfaction. These findings suggest that operators generally feel confident in their ability to manage core business functions but see considerable opportunities to turn steady execution into greater growth and value, not just greater efficiency.
Overall, the findings suggest that respondents do not view their organizations as fundamentally underperforming; rather, most believe their firms are operating at an acceptable baseline while leaving considerable value unrealized. Across every business function measured, the share of respondents expecting strong or industry-leading performance at full potential exceeds current ratings by roughly 19 to 29 percentage points, underscoring the extent to which operational, technological and organizational barriers are perceived to constrain business outcomes.
Investment Changes Needed to Improve Performance
With an eye toward forward-looking expectations, participants were asked to share what investments or changes they believe would most improve their companies' performance over the next 12 months. The data show that respondents believe the strongest path to improved company performance stems from building employee capability and strengthening operational execution. The top-selected investment was staff training, development and reskilling, chosen by 46% of respondents, followed by standardizing operating procedures across the portfolio, chosen by 38%. This suggests that companies see clear performance gains from better-trained teams and more consistent execution.
Technology is also a major improvement lever, but it appears to be viewed as part of a broader operational strategy. Expanding the use of AI and automation was selected by 34% of respondents, while adopting new technology platforms was chosen by 28%. Smaller shares prioritized improving data and analytics, consolidating systems or centralizing operations, indicating that companies may be focused first on tools that reduce friction and improve efficiency.
Staffing remains another important area, with 31% identifying hiring additional staff as a performance-improving change. By contrast, only 2% selected reducing headcount, suggesting that respondents largely see people as a resource to strengthen rather than a cost to cut.
The Path to Better Performance
When asked about the biggest barriers to better performance, respondents most often cited technology and automation, staffing and retention, and process and operational efficiency.
Technology and automation were the most frequently cited areas for improvement. Respondents generally viewed technology as an important driver of future performance, but their comments suggest the larger challenge is not simply adopting new tools; it is integrating and using them effectively. Many pointed to fragmented systems, disconnected workflows, manual tasks and challenges scaling automation or AI. Others called for better platform integration, stronger reporting capabilities and technology that reduces administrative burden instead of adding complexity.
Workforce challenges were another major theme. Respondents cited ongoing difficulty hiring and retaining qualified employees, providing adequate training and maintaining enough staff to meet operational demands. Many comments reflected concerns about employee capacity, turnover and the challenge of balancing daily responsibilities with longer-term priorities. These findings emphasize why rental housing operators continue to prioritize future investments in staff training, development and additional hiring.
Process and operational efficiency also surfaced repeatedly. Operators pointed to inconsistent workflows, limited standardization, repetitive manual tasks and reactive operating models as barriers to stronger performance. Many emphasized the need for more consistent execution through standardized processes, clearer responsibilities, and better use of existing procedures.
Together, the responses suggest that operators see performance improvement as a connected challenge across people, processes and technology. While the specific obstacles varied, the themes were consistent: Reduce manual work, improve operational efficiency, strengthen workforce capabilities and build systems that allow employees to spend less time reacting to daily issues and more time on strategic work that drives business performance. As more of that work shifts to AI and automation, the ability to trust those systems (through clear oversight, auditability and guardrails) becomes as important as the technology itself.
Rental Housing Operations: Staffing
Staffing remains both a persistent challenge and a clear opportunity to improve operational performance. For the second consecutive year, we examined how industry professionals allocate their workdays to identify shifts in time use. Respondents still spend most of their workweek on routine operations and issue resolutions, but the results point to a strong desire to shift toward more strategic and relationship-focused work. In 2026, respondents reported spending 38% of their time on routine operational work and 26% on reactive, issue-driven tasks, meaning nearly two-thirds of the typical workweek is consumed by administrative, manual, urgent or troubleshooting activities. By contrast, less time is devoted to higher-value work, with respondents spending an average of 20% on stakeholder engagement and 17% on strategic or performance-driven activities.
Compared with 2025, time spent on routine operational work modestly declined, from 42% to 38%, while stakeholder engagement increased from 17% to 20%. Strategic and performance-driven work was largely unchanged, rising by one percentage point to 17%. These shifts suggest that organizations are making gradual progress in reducing routine administrative burdens, though reactive work continues to take up a significant share of employee time.
As in last year's survey, respondents were also asked to describe their ideal distribution of time across the same categories. They indicated a preference for a more balanced workweek, with routine operational work still receiving the largest share at 31%. However, respondents would like to devote substantially more time to higher-value activities, including strategic or performance-driven work at 26% and stakeholder engagement at 25%.
While respondents consistently expressed a desire to shift more time toward strategic and stakeholder-focused activities, the continued prominence of routine operational work in the ideal allocation suggests that many view these responsibilities as an enduring and necessary component of their roles. Rather than seeking to eliminate work, respondents are seeking to preserve essential operational work while creating more capacity for planning, performance improvement, innovation, team development and proactive relationship-building. The consistent gap between actual and ideal time allocation suggests that reducing time spent on routine and reactive work isn't just an efficiency question. It's a precondition for the kind of proactive, relationship-and performance-focused work respondents say they want more of.
Role-Based Differences Reveal Shifts in Time Commitments
Although respondents across all roles expressed a desire to spend less time on routine and reactive work and more time on strategic priorities, current time allocations vary considerably across job functions. Owners, executive leaders and regional managers reported spending roughly 60% of their time on routine operational and reactive activities collectively, limiting the time available for planning, long-term growth objectives and performance improvement. Under ideal conditions, each group would substantially increase the share of time devoted to strategic and performance-driven work, particularly owners, who would like to nearly double their strategic focus from 20% to 39% of their work week.
Maintenance professionals stand apart from other roles because their work is more reactive by nature, with nearly 40% of their time spent responding to issues—the highest share across all roles. Although reactive work is an unavoidable part of maintenance operations, respondents would prefer to reduce routine tasks and spend more time on preventive and planned activities. Leasing professionals, by contrast, dedicate a larger share of their time to stakeholder engagement (27%) than any other role surveyed, reflecting the customer-facing nature of their responsibilities. However, routine operational work remains their largest time commitment, accounting for 35% of the typical workweek. Like other respondents, leasing professionals expressed a desire to shift time away from administrative tasks and toward higher-value engagement activities.
Taken together, these findings reinforce the importance of role context when evaluating ideal work allocation. While respondents generally express a desire to dedicate more time to strategic and stakeholder-focused activities, role-level differences suggest that ideal workloads are shaped by the nature of the work itself. Leadership and portfolio management roles show the strongest preference for strategic activities, while operational roles continue to view routine and reactive responsibilities as essential components of their day-to-day responsibilities. The consistency of this pattern year-over-year suggests that improvements in staffing, process efficiency, automation and technology could help employees across all functions spend more time on higher-value work.
Despite Operational Pressures, Employee Engagement Remains High, but Owners and Property Managers Report More Strain
Given the divergence between what respondents would like to focus on versus what they are actually doing, we asked them to share how engaged they felt with their work over the past 12 months. The results highlight that most respondents feel positively connected to their work. Nearly three-quarters (74%) described themselves as engaged, meaning they are enthusiastic about and committed to their work.
At the same time, about one-quarter (24%) said they are not engaged, suggesting they are doing the work but with limited extra energy or passion. Only a small share (3%) reported being disengaged, describing themselves as unhappy and disconnected from their work.
Engagement levels by industry roles reveal a more nuanced view of workforce health. Engagement remains comparatively strong among executive leadership (83%), leasing professionals (79%), maintenance professionals (76%) and portfolio managers (75%). However, signs of disengagement are slightly more pronounced among owners, property managers and corporate operations staff.
Industry Professionals Report High Levels of Frequent Workplace Stress
For many professionals in rental housing, the workload carries myriad challenges across a wide range of issues. Many times, that can place noticeable burdens on well-being. We asked survey participants to share how often their work left them feeling a lot of stress.
The findings show that workplace stress is common, though its frequency varies. The largest share of respondents (41%) said their work causes significant stress some days, roughly two to three days per week. Another 26% reported high stress more often: 18% experience it most days and 8% experience it every day.
By contrast, about one-third of respondents experience high stress less frequently: 29% said it happens rarely, and only 4% said it never occurs. Overall, the results suggest that while daily high stress affects a smaller share of respondents, most experience significant work-related stress at least occasionally during a typical week.
Together, the engagement and stress findings suggest that employees remain committed to their work, even as they operate under substantial pressure. The combination of high engagement and elevated stress reinforces a broader theme: Challenges are driven less by workforce motivation and more by capacity, workload distribution and operational complexity.
Most Organizations Prioritize Employee Engagement, but Full Integration Remains Limited
As a follow-up to the issue of workplace stress, respondents were further queried about whether their organizations actively prioritize employee engagement and team culture as part of operational performance strategy. In a sign that companies recognize rental housing is a people-centric endeavor, survey results suggest that employee engagement and team culture are widely recognized as part of operational performance strategy, but they are not always fully embedded in day-to-day operations.
A majority of respondents said these areas are either a "core priority embedded across all operations" (26%) or an "important priority, but not consistently embedded" (33%). At the same time, a sizable minority indicated a weaker organizational focus. About 19% said engagement and culture are considered only occasionally in decision-making, while 23% said there is limited focus or that they are not a priority. These numbers hint there may be a meaningful gap between recognizing the value of engagement and team culture and consistently integrating them into operational strategy.
Rental Housing Operations: Technology
In today's rental housing operations, technology is shifting toward a more visible profile. When asked about their organizations' primary focus on technology investment, respondents indicated that it is centered overwhelmingly on AI, automation and operational efficiency. Many respondents described their organizations as exploring or implementing AI to reduce manual work, streamline workflows, automate repetitive tasks, improve reporting and free staff time for higher-value work. Common use cases include leasing, maintenance work orders, tenant/resident communication, reminders, data entry, reporting and back-office processes.
A second major theme is system integration and modernization. Respondents frequently mentioned property management platforms, customer relationship management (CRM) tools, resident portals, online payments, paperless processes, centralized reporting and better use of existing software. Many organizations appear focused less on flashy innovation and more on practical improvements and systems that work together instead of in parallel, that make day-to-day operations smoother, more accurate and easier for staff, residents, owners and vendors.
At the same time, the responses reveal uneven technology maturity. Some companies are highly focused on AI and digital transformation, while others report minimal additional investment, uncertainty, lack of training, limited resources, cost concerns or slow adoption. Several respondents also emphasized the need to balance automation with human service, noting that technology should improve efficiency without diminishing resident relationships, customer experience or service quality. Overall, the findings point to strong interest in technology as a tool for efficiency and modernization, but with significant variation in readiness, execution and organizational commitment.
Training, Time Constraints and User Adoption Remain the Biggest Barriers to Technology Implementation
The challenges associated with implementing new technology are present across a number of organizations. When asked about additional details, respondents indicated that the biggest challenges in implementing new technology are less about interest in innovation and more about the practical realities of adoption. The most recurring concerns are training, time and learning curves, with many respondents saying staff needs more instruction, support and dedicated time to learn new systems while still managing day-to-day operations.
A second major theme is changing management and user adoption. Respondents frequently mentioned resistance to change, difficulty getting employees, owners and residents to use new tools, and the challenge of bringing less tech-savvy or long-tenured staff along. This suggests that successful implementation depends heavily on communication, buy-in, and organizational readiness.
Major Challenges to Technology Implementation
| Challenge | % of responses | What respondents mean | Pull quotes |
|---|---|---|---|
| Training & learning curve | 31% | Staff lacks the time, knowledge or support needed to learn and effectively use new technologies. | "Finding time to learn and implement AI." "Training. We don't have the time to train and roll out new software properly." |
| General technology complexity | 10% | Technologies can be difficult to understand, configure, maintain or adapt to business needs. | "Many systems don't speak to each other." "Technology companies have bigger promises than delivery." |
| Change resistance & user adoption | 10% | Employees, managers, residents or owners are reluctant to change established processes. | "Getting employees to embrace change." "Older staff and small organization." |
| Time & capacity constraints | 8% | Teams are stretched thin and lack time to research, implement, and manage new tools. | "Not enough employees and time." "Having the time to actually work on it." |
| Cost & budget constraints | 8% | Technology investments are difficult to justify or fund. | "Cost vs. value of the technology." "Having an owner willing to spend the money." |
| Resident/client adoption | 5% | Residents and clients may be unwilling or unable to use digital tools. | "Tenant and owner refusal to use systems." "Older residents are not familiar with the technology currently in place." |
Note: The percentages represent the share of respondents whose open-ended comments were coded into each theme. Because this was a qualitative question, the findings illustrate the most commonly cited barriers rather than direct ratings of importance.
Respondents also point to cost, integration and system fit as significant barriers. Many organizations worry about budgets, ROI, owner approval, duplicate data entry, multiple disconnected platforms and whether new tools will integrate smoothly with existing property management, CRM and operational systems. Some also raise concerns about AI accuracy, trust, compliance, cybersecurity and maintaining personal service for residents. Overall, the findings suggest that technology adoption is viewed as valuable, but only when it is well-supported, affordable, easy to use, integrated with existing workflows, and clearly improves efficiency without adding complexity.
Technology Complexity Persists as Employees Navigate Multiple Daily Systems
Most respondents rely on multiple software platforms to manage their daily responsibilities. Only 15% report using a single software tool or login during a typical workday, while more than eight in ten use two or more systems. The most common response was three separate tools or logins (26%), followed by two tools (24%) and four tools (17%), while 18% report using five or more software tools each day.
These findings suggest that while technology has become increasingly embedded in rental housing operations, many organizations continue to navigate fragmented technology ecosystems that require employees to move between multiple systems to complete routine tasks.
The results help explain why technology integration, automation and process efficiency have been identified as key opportunities for improvement. As software portfolios expand, the challenge increasingly becomes not just adopting technology, but also ensuring that systems work together in a way that reduces administrative burden and improves operational efficiency.
Organizations Can Easily Access Current Performance Data but Struggle With Predictive Intelligence
Industry operators reported strong access to historical and current performance data, suggesting that most organizations can effectively track what has happened and monitor what is happening in real time. Nearly all respondents (93%) indicated that current performance data is easy to access, while 79% reported similar access to historical information. However, access becomes significantly more challenging when organizations move beyond monitoring performance to anticipating and shaping future outcomes. More than half of respondents reported difficulty accessing predictive data (53%) and prescriptive data (54%), making these the least accessible forms of performance intelligence.
The findings suggest that while many operators have established systems for reporting and operational visibility, fewer have the tools, processes or analytical capabilities needed to forecast future performance and identify recommended courses of action. This gap is particularly notable given that respondents also identified forecasting, decision-making and technology management as areas with some of the largest differences between current performance and perceived potential.
As operators increasingly seek to improve efficiency, optimize performance and maximize NOI growth, the ability to move from descriptive reporting to predictive and prescriptive decision-making may represent a significant opportunity for future investment.
Artificial Intelligence Is Delivering Measurable Value, but Transformational Impact Remains Uneven Across Organizations
AI adoption continues to move beyond experimentation and into practical business applications. More than two-thirds of respondents reported that AI is generating at least some value for their organizations, with 33% indicating that AI is delivering clear, measurable improvements and 22% reporting marginal performance gains. Another 13% described AI as revolutionizing how their organizations operate, suggesting that a growing segment of the industry is beginning to realize transformative benefits from AI-enabled tools and workflows.
At the same time, relatively few respondents expressed dissatisfaction with AI performance. Only 4% characterized AI as overhyped and falling short of expectations, while 18% reported that AI has had limited or no impact to date. An additional 10% indicated that their organizations are not currently using AI.
The findings suggest that the conversation around AI is increasingly shifting from whether organizations should adopt AI to how effectively they can implement and scale it to drive performance outcomes. While most respondents reported some degree of value, the wide range of perceived impact indicates that organizations remain at different stages of AI maturity. As adoption continues to expand, the ability to integrate AI into workflows, decision-making and operational processes, and to ground it in real context about how the business runs may increasingly determine the extent of performance gains realized. That pattern also suggests AI performs best when it has real context about how the business runs, not when it's applied as a generic capability layered on top of existing tools.
Most Adopted Technologies and Operational Changes Deliver Positive Performance Gains
Respondents overwhelmingly reported positive outcomes from the technologies and operational changes they have implemented. Across every solution evaluated, positive impacts substantially outweighed negative impacts, suggesting that operators generally view these investments as enhancing performance rather than creating additional operational burdens.
Resident self-service technology generated the strongest results, with 79% of respondents reporting a positive impact on performance and just 2% reporting a negative impact. Application screening and fraud detection technology (77%), general-purpose AI tools such as ChatGPT and Copilot (77%) and standardized operating procedures (73%) also ranked among the highest-performing solutions. These findings suggest that technologies that streamline routine interactions, reduce administrative workload and improve operational consistency are generating the greatest perceived value.
More advanced operational capabilities also delivered strong results. Respondents reported positive impacts from AI features embedded within core property management software (71%), real-time dashboards and analytics (70%), unified data systems (68%) and centralized operations (67%). Together, these findings reinforce the growing importance of connected systems, data visibility and automation in driving operational performance.
Notably, even technologies with lower adoption rates generated favorable outcomes among users. Sixty percent of respondents reported positive impacts from custom AI tools developed internally, while 58% reported positive results from AI features embedded in other property management platforms. Although adoption remains relatively limited for some of these solutions, the findings suggest that organizations implementing more advanced technologies are generally realizing measurable benefits.
Technology Adoption Gaps Are Concentrated Among Smaller Operators
While adoption rates are high for many operational technologies, the remaining adoption gaps appear to be concentrated among smaller operators. Respondents managing fewer than 1,000 units account for 73% of all reported non-adoption, compared with 24% among mid-sized operators and just 2% among those managing 10,000 or more units. The findings suggest that larger organizations have largely moved beyond foundational technology adoption, while smaller operators may face greater resource, staffing and implementation constraints.
Several technologies have achieved near-mainstream adoption across the industry; however, the largest adoption gaps are concentrated among more specialized or resource-intensive initiatives. Nearly one-third of respondents have not adopted building technology solutions (31%), while adoption remains considerably lower for AI features embedded within other property management platforms (39%), custom AI tools developed internally (43%) and offshore staffing models (46%). These findings suggest that while many operators have embraced foundational technologies, adoption of more advanced AI-enabled capabilities remains uneven across the industry.
Taken together, the results point to a maturing technology landscape where the challenge is increasingly less about whether organizations are using technology and more about the depth and sophistication of that adoption.
Key Takeaways
1. Performance remains strong, but operators see significant untapped potential — most respondents report positive company performance and NOI growth, yet nearly all believe performance could improve substantially under optimal conditions.
2. Operational efficiency is the industry's defining challenge — manual processes, staffing constraints, and execution gaps continue to hold back business outcomes.
3. Scale matters — large operators are significantly more likely to report top-tier performance than smaller organizations.
4. AI is generating value, but implementation determines impact — organizations reporting the strongest AI impact are also the most likely to report stronger financial outcomes.
5. Technology adoption is maturing — the challenge is increasingly less about adopting technology and more about integrating, scaling and optimizing it.
6. Employees want greater capacity for strategic work — respondents continue to seek a better balance between operational responsibilities and higher-value activities that drive long-term performance.
7. Future gains will come from aligning people, processes, and technology — the industry's greatest opportunities lie in improving workforce capabilities, operational execution and technology effectiveness simultaneously.
Taken together, these findings describe an industry in transition: From measuring success primarily by task efficiency toward a broader definition of performance that includes value created for residents, investors, owners and staff alike.
Methodology
State of Rental Housing 2026: Performance, People & Technology is based on responses from over 2,000 rental housing professionals representing a diverse range of portfolio sizes, property types and organizational roles. Respondents included property managers, accountants, assistant property managers, operations managers, leasing professionals, regional managers, owners, executives and other industry stakeholders. Survey participants represented organizations ranging from small operators managing fewer than 50 units to large portfolios exceeding 30,000 units. Market-rate multifamily housing comprised the largest segment of respondents' organizations, followed by single-family rental, commercial, affordable housing, mixed-use and other residential property types.
The survey examined rental housing performance, staffing, technology adoption, operational challenges, workforce engagement, and artificial intelligence utilization. Questions included a combination of multiple-choice, rating-scale and open-ended response formats designed to capture both quantitative trends and qualitative perspectives from industry professionals. Open-ended responses were analyzed and categorized into common themes to identify recurring challenges and opportunities affecting operational performance.
Percentages may not total 100% due to rounding. For questions allowing multiple responses, totals will exceed 100%. Unless otherwise noted, results reflect responses from the full survey sample. Certain questions were analyzed using smaller respondent groups based on eligibility criteria.
For reporting purposes, individual respondent job titles were consolidated into broader role categories to facilitate the analysis and presentation of results. The consolidated categories are shown in the table below.
| Consolidated role categories | Roles included |
|---|---|
| Owners | Independent rental owner, owner/president/principal |
| Executive leadership | Corporate executive/VP/SVP/EVP/RVP, chief financial officer |
| Regional management | Regional property manager/RPM, association manager |
| Property management (on-site) | Property manager, assistant property manager |
| Leasing professionals (on-site) | Leasing professional, leasing manager |
| Maintenance professionals (on-site) | Maintenance manager, maintenance technician |
| Corporate operations & support | HR manager, compliance manager, accountant, asset manager, broker, marketing professional, office/operations manager, IT support or consultant, etc. |
Survey Respondent Profile
The survey reflects a diverse cross-section of the rental housing industry, with respondents representing organizations of varying portfolio sizes, property types and professional roles. The largest share of respondents manages portfolios containing 150 to 499 units (32%), followed by operators managing 500 to 999 units (17%).
Market-rate multifamily housing represents the largest property type in the sample, with 68% of respondents indicating involvement in the sector. Single-family rentals (50%), commercial properties (25%) and affordable housing communities (24%) also comprise significant portions of the respondent base, reflecting the diverse operating environments represented in the survey. Also, respondents span a diverse range of industry roles, with the largest share (44%) coming from property management positions.
Note: Totals may not sum up to 100 due to rounding.
About the Authors

George Ratiu is Vice President of Research at the National Apartment Association (NAA), leading the organization's economic, housing market, and policy research. His work delivers insight for rental housing providers, policymakers and industry stakeholders on macroeconomic conditions and structural trends shaping the US rental housing sector.
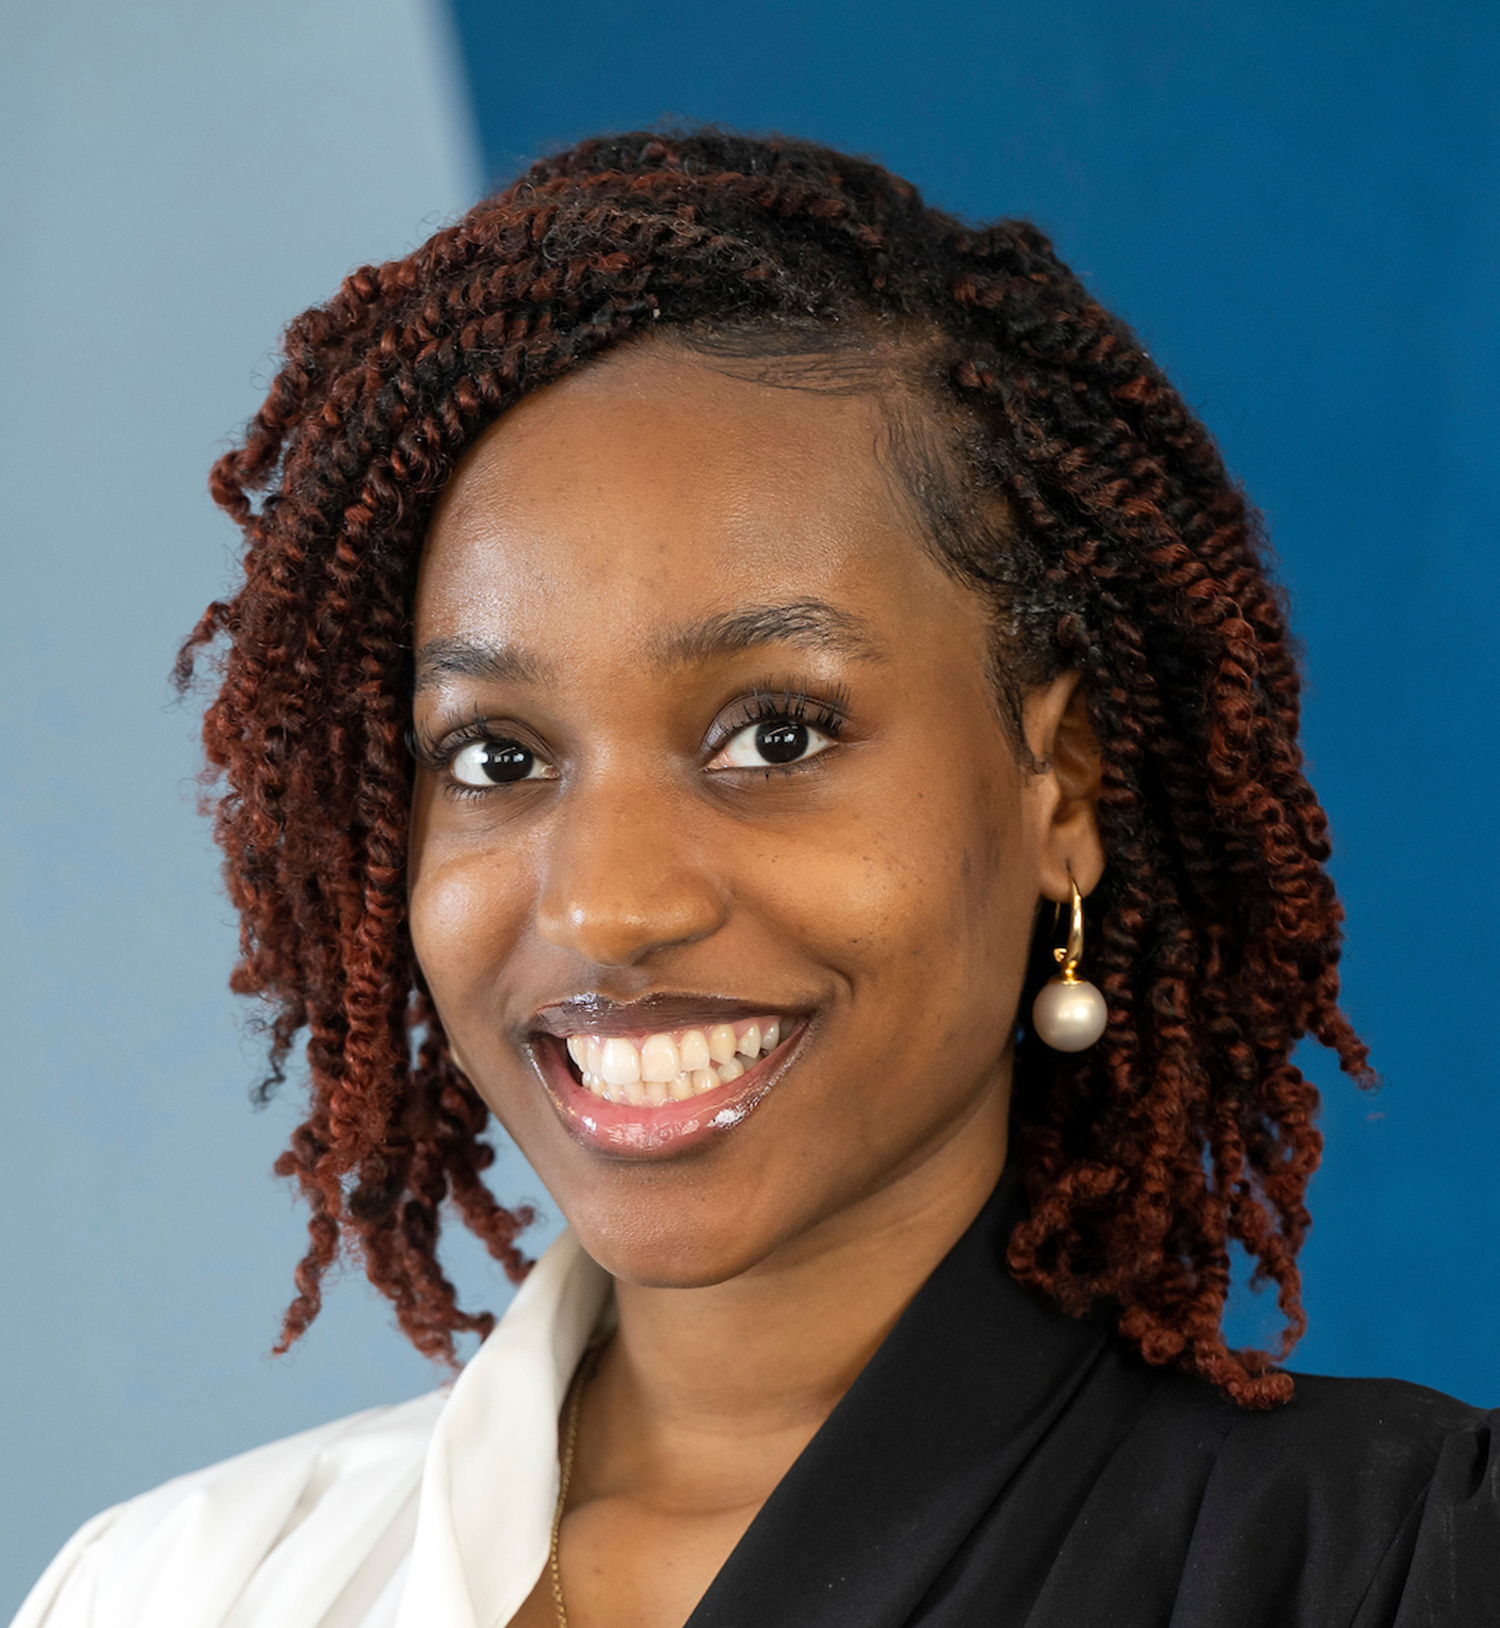
Eri Bajomo is Manager of Industry Research at the National Apartment Association (NAA), where she leads market intelligence and economic research focused on the US rental housing industry. Her work examines the economic, operational and market forces shaping housing performance across multifamily, single-family rental, and other housing segments, translating complex research into actionable insights that inform business strategy and industry decision-making.